in New London, CT
Finding the perfect used car is an exciting step, but it is just one part of your overall vehicle budget. A crucial, and often overlooked, expense is auto insurance. For drivers in New London, Connecticut, understanding the factors that determine your insurance premium is key to managing the total cost of owning a car. Rates can vary significantly based on a wide range of variables, from the type of vehicle you choose to your specific neighborhood within the city. This guide is designed to demystify car insurance costs in New London, providing you with the knowledge to make informed decisions. We will explore the key elements that insurers consider, offer tips for finding competitive rates, and help you prepare for this essential aspect of car ownership before you even schedule a test drive.
Preparing for your vehicle purchase involves more than just selecting a model and securing financing. By researching potential insurance costs ahead of time, you can create a more accurate and sustainable budget. This proactive approach helps avoid surprises and ensures that the monthly payment for your ideal car, combined with its insurance premium, fits comfortably within your financial plans. Let our team help you navigate the entire process, from exploring affordable financing options to understanding the ongoing costs of your next vehicle.
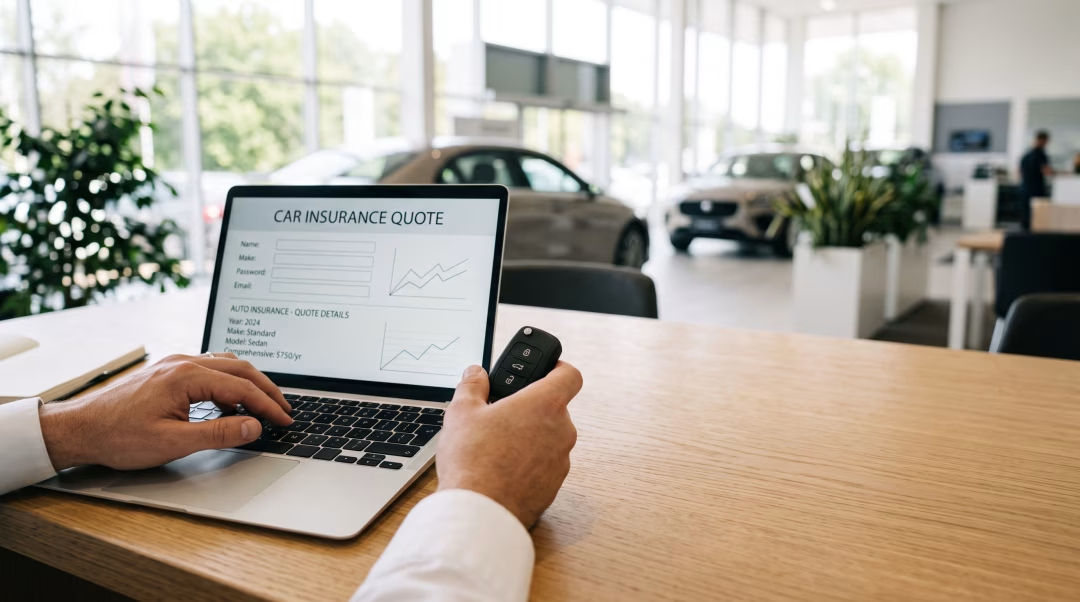
Key Factors Influencing Your New London Car Insurance Rates
Auto insurance companies use a complex algorithm to calculate your premium, assessing risk based on a collection of personal and vehicle-specific data. No single factor tells the whole story; instead, it is the combination of these elements that creates your unique insurance profile. For residents of New London, CT, some factors carry more weight than others due to local driving conditions and state regulations. Understanding these components can empower you to take steps that may positively influence the quotes you receive.
Below are some of the most significant factors that insurers analyze when determining your rates.
- Driving History: This is one of the most critical factors. A clean record, free of accidents, tickets, and DUIs, signals to insurers that you are a low-risk driver. Conversely, a history of violations can lead to significantly higher premiums.
- Vehicle Make and Model: The car you drive plays a huge role. Insurers consider the vehicle's value, repair costs, theft rate, and safety ratings. A reliable used sedan may be cheaper to insure than a high-performance sports car or a large luxury SUV. Before you finalize your purchase, it is wise to compare insurance quotes for a few different models you are considering from our vehicle inventory.
- Your Location in New London: Where you live and park your car matters. Insurers use ZIP codes to assess risk based on local statistics for theft, vandalism, and accidents. Urban areas like New London may have higher rates than more rural parts of Connecticut due to greater traffic density and a higher likelihood of claims.
- Age and Driving Experience: Younger, less experienced drivers typically face higher insurance costs due to a statistically higher risk of accidents. Rates often decrease as drivers get older and gain more experience behind the wheel, assuming they maintain a good record.
- Credit-Based Insurance Score: In Connecticut, insurers are permitted to use a credit-based insurance score as one factor in setting premiums. This score is different from your standard credit score but is derived from your credit history. Managing your credit responsibly can be beneficial, and we specialize in helping customers explore bad credit car loans in New London.
- Coverage Choices and Deductibles: The amount and type of coverage you select directly impact your cost. Opting for higher liability limits or adding optional coverages like collision and comprehensive will increase your premium. Similarly, choosing a lower deductible (the amount you pay out-of-pocket in a claim) means a higher premium, while a higher deductible can lower it.
Strategies for Lowering Your Insurance Premiums
While some rating factors like your age are beyond your control, there are many proactive steps you can take to manage and potentially reduce your auto insurance costs. Getting a favorable rate requires a bit of research and strategic decision-making. Whether you are a first-time car buyer or a seasoned driver, these tips can help you find a policy that provides the protection you need without breaking your budget.
- Compare Quotes: Do not accept the first quote you receive. Rates can vary dramatically between insurance carriers for the exact same coverage. Obtain quotes from at least three different companies, both national and local, to ensure you are getting a competitive price.
- Ask for Discounts: Insurers offer a wide variety of discounts. Common examples include good student discounts, safe driver discounts for having a clean record, and multi-policy discounts for bundling your auto insurance with a home or renters policy from the same company.
- Choose Your Vehicle Wisely: As mentioned, the car you drive is a major cost factor. When browsing for cheap used cars in New London, consider models known for their safety and lower repair costs, as they are often less expensive to insure. Get insurance quotes on potential vehicles before you buy.
- Increase Your Deductible: If you can comfortably afford to pay more out-of-pocket in the event of a claim, raising your collision and comprehensive deductibles from $250 or $500 to $1,000 can result in a noticeable reduction in your premium.
- Review Your Coverage Annually: Your needs can change over time. As a car gets older and its value decreases, you might consider dropping collision or comprehensive coverage, especially if its value is less than what you would pay in premiums plus the deductible.
Navigating Insurance and Financing Together
For most buyers, insurance and financing are linked. If you plan to finance your vehicle, the lender will almost certainly require you to carry both collision and comprehensive coverage to protect their investment. This is an important consideration when you are working on your budget for a car. Our finance team is experienced in working with drivers from all backgrounds, including those seeking used car financing in New London with various credit situations. We can help you understand the full financial picture so you can choose a vehicle and a loan that align with your insurance requirements and overall budget.
Why is car insurance in New London, CT potentially more expensive than in rural areas?
Car insurance rates are often higher in urban areas like New London compared to rural towns due to increased population density. This leads to more traffic, a higher statistical probability of accidents, and greater risks of theft and vandalism, all of which are factors that insurance companies consider when calculating premiums for a specific ZIP code.
What are the minimum car insurance requirements in Connecticut?
As of the latest regulations, Connecticut requires all drivers to carry liability insurance. The minimum coverage is typically expressed as 25/50/25, which stands for $25,000 for bodily injury per person, $50,000 for bodily injury per accident, and $25,000 for property damage per accident. Uninsured/underinsured motorist coverage is also required.
Does the type of used car I buy significantly affect my insurance rate?
Absolutely. The make, model, year, and value of your vehicle are major factors. Cars that are expensive to repair, have high theft rates, or lack modern safety features generally cost more to insure. Conversely, a reliable used sedan or SUV with a strong safety record will typically have lower insurance premiums. It is always a good idea to get insurance quotes for specific vehicles you are considering before making a final decision.
Can I get car insurance if I have a bad credit history?
Yes, you can still get car insurance even with a challenging credit history. While Connecticut allows insurers to use a credit-based insurance score as one of many factors, it is not the only one. Having a less-than-perfect score might result in higher premiums, but you can still find coverage by shopping around with different carriers. Focusing on other factors, like maintaining a clean driving record, can help offset the impact.
What is the difference between collision and comprehensive coverage?
Collision and comprehensive are two distinct types of optional coverage. Collision coverage helps pay for repairs to your vehicle if it is damaged in an accident with another object, like another car or a stationary object. Comprehensive coverage helps pay for damages from non-collision events, such as theft, vandalism, fire, hail, or hitting an animal. If you finance a car, your lender will typically require you to have both.
